

share
Will Your Pension be enough?
Tell us about your pension, savings and lifestyle goals and we'll model your projected retirement income against what you actually want to spend. Our Retirement Readiness Scorecard will tell you where you stand in just 10 minutes. With full Irish Tax built in.
informed decisions blog
Before You Retire in Ireland: 5 Decisions You Can't Undo
September 28, 2026
What happens to the Standard Fund Threshold in Ireland after 2029?
The Standard Fund Threshold reaches €2.8m in 2029. From 2030, Revenue says it will be indexed to growth in average weekly earnings, so the figure will depend on how Irish earnings move rather than on a fixed schedule.
Here's a question I wish more people asked themselves a year or two out from retirement. It isn't "will I have enough money?" It is: which of the things on my retirement checklist can I still change my mind about next year? And which ones are irreversible?
If I could hand you one thing when you are working out what to do before you retire in Ireland, it would be a letter to yourself, written 12 months before you finish. Not to warn you about markets, or to talk you out of that nice camper van you bought for the family. Just to say this: of everything on your checklist, four or five items are doors. Once they're closed, they're closed and they don't ever open again.
Our essential pre-retirement checklist for Ireland covers the wider to-do list. This piece is about the doors, taken one at a time, counting down.
Door five: your €200,000 tax-free lump sum is for life, not per pension
Your tax-free retirement lump sum is not a per-pension-pot entitlement. Revenue's own wording is blunt about this: it is a lifetime entitlement of €200,000 on retirement lump sums from all sources, however many pension pots you've picked up along the way. Above that, the slice from €200,001 to €500,000 is taxed at the standard rate of 20%, and anything beyond €500,000 under PAYE.
So picture someone who took a €200,000 lump sum out of an old buyout bond at 58, for argument's sake, because it's what they wanted at the time. That's their entire lifetime allowance for tax-free lump sums gone, in that one sitting. Any lump sum they draw from other pots for the rest of their life is taxable: 20% on the next €300,000, then taxed as income. That is not to say they shouldn't have taken it. But that's you done in terms of tax-free lump sum from pensions. Right. Once it's closed, it is closed.
Door four: buy an annuity and the capital is gone
This one's short and it's blunt. Buy an annuity and that capital is gone. Door closed.
I'm not pro nor anti annuities. But the capital, once you hand it over to the insurance company, is gone in that instant. You've swapped it permanently for an income for life, and there's no undoing that swap.
An approved retirement fund (ARF) leaves the door more open. Revenue allows ARF funds to be used at any time to buy an annuity, so at 75, at 80, or whenever annuity rates look attractive to you, some or all of the ARF can go that way. You cannot travel the other direction, from annuity back to ARF.
For plenty of people, that certainty is exactly what they want and need, and it is worth every cent. A bit like buying the good wellies instead of the ones from the two euro shop, which some of us did. Just make that decision once, deliberately. We went through the numbers in annuity vs ARF for a €1 million pension pot in Ireland.
Door three: the calendar, and the Standard Fund Threshold
This is the detailed one, so do bear with me, and I hope I don't make a hames of the explanation.
The Standard Fund Threshold (SFT) is the lifetime cap on tax-relieved pension benefits you can draw. Go over it and chargeable excess tax applies at 40% on the amount above the cap. That tax is ring-fenced: there's no relief against it, apart from one nuance I'll come to.
Under the Finance Act 2024 it is rising on a set schedule: €2m in 2025, €2.2m in 2026, €2.4m in 2027, €2.6m in 2028 and €2.8m in 2029, then in line with average earnings. We covered the background in what the new Standard Fund Threshold means for your retirement.
So for anyone sitting near the threshold, the tax year you choose to crystallise isn't a trifling matter. It can be a €200,000 swing in your allowance from one year to the next.
Who pays chargeable excess tax in Ireland, and when?
Chargeable excess tax is deducted by the pension administrator or PRSA provider and paid to Revenue, within three months of the end of the month in which the event occurs. It usually comes out of the pension fund itself.
Maggie, 61, and a €2.6m pension
Let's take a fictitious character, Maggie. Any similarity to any real person is honestly quite coincidental. Maggie is 61, sold her business a couple of years ago and spends most of her time on the water or in the mountains. Rental income and dividends pay for her lifestyle. But she has these looming pension assets: €2.6m, all in one scheme, with no option to phase it. For her it's very much a decision of "I trigger or I don't".
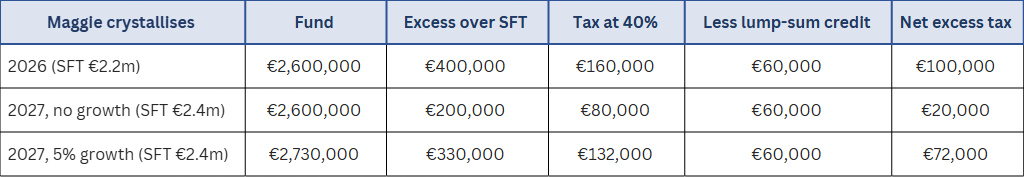
If she crystallises in 2026, her excess over the €2.2m threshold is €400,000, and the tax at 40% is €160,000. Say she also takes a €500,000 lump sum. The first €200,000 is tax-free; the remaining €300,000 is taxed at 20%, so €60,000. Here's the interesting nuance: that €60,000 is credited against the excess tax. Her net excess tax is €100,000, deducted by the administrator and paid to Revenue from her pot.
Now say she waits until 2027, when the threshold is €2.4m, and the fund value is unchanged. Her excess halves to €200,000 and, after the same credit, her net excess tax is €20,000. That's €80,000 less paid to Revenue. Not €80,000 of income before tax: €80,000 less tax, full stop.
All things are not usually equal
Before we all get carried away and reschedule our crystallisation events, a bit of reality. That €80,000 assumes her fund stands still. If she's heading for an ARF, as the majority of people appear to be, she is more than likely still invested, and her pot will move.
Assume even 5% growth into 2027. She crystallises €2.73m, not €2.6m, and pays €72,000 (the last row above). Against the €100,000 she would have paid this year, most of the saving is gone. Grow a little faster and it's gone altogether.
Waiting can give you access to a larger threshold, at least for the next few years. But if you're well invested and markets deliver anything like their long-term average, it is a very difficult game to play. Because once you crystallise, the pot can grow like billy-o, and excess tax is a thing of the past.
It's kind of like trying to time the market, and only hindsight will tell us. Crystallising also takes time, and values can and will move between the day you decide and the day it's triggered. That's just the reality of it. Ultimately, it is a case of making the decision that makes sense, then moving on.
Door two: the relief that leaves with your last payslip
This is one I see a fair few people walk through, and we usually meet them after the event.
Pension tax relief on your own contributions is a real opportunity in your 50s and beyond. Between 55 and 59 you can contribute up to 35% of your earnings personally with full income tax relief; from 60, it's 40%. Both apply to earnings up to a cap of €115,000, so that's up to €40,250 a year between 55 and 59, and €46,000 at 60 or over. A very generous allowance, and an awful lot of people don't use it.
An AVC through your scheme, a separate AVC, a PRSA: find a way in. If you own and run your own company, it may be paying employer contributions for you while you make none personally. Nothing stops you contributing personally too, often to the same PRSA. And if you have cash on deposit earning next to nothing that you won't need, raising your contributions and using that cash to cover the drop in take-home pay can be a no-brainer.
Watch the timing. An awful lot of people finish up in spring. The limit is a percentage of that year's earnings, so a few months' salary leaves less room than a full year. Have you used it? And if you've already reached the higher rate in that final year, does it make sense to draw a pension this year, or wait for the next tax year?
Door one: the order of it all
The last door is the order you take the others in. Where are you with the SFT today, and where will you be when you actually crystallise? Is drawing pension income tax-efficient this year or next? Is there room for more contributions before your earnings stop? And what's your lump sum strategy: up to €200,000, or beyond it at 20%, compared with leaving it in the pot and paying tax on drawdown, potentially at a much lower rate? Potentially.
Pre-retirement checklists are absolutely great to do. Some of the doors will stay open. Some, once you walk through, you cannot go back. Talk to your pension administrator about the rules and your flexibility, or speak to a financial planner who knows this area. That conversation could be worth an awful lot to you.
I hope this helps.
Paddy
Disclaimer
The content of this site including blogs and podcasts is for information purposes only. Everybody’s financial situation is different and the content we share on our site and through podcasts may not be applicable to you.
The articles, blogs and podcasts are not investment advice. They do not take account of your individual circumstances, including your knowledge and experience and attitude to risk. Informed Decisions can’t be held responsible for the consequences if you pursue a course of action based on the information we share
How much can I contribute to a pension at 50 to 54 in Ireland?
Pension tax relief at 50 to 54 applies to personal contributions of up to 30% of earnings, capped at €115,000 of earnings. That means up to €34,500 a year, rising to 35% at 55 and 40% at 60.
You may also like...
Not sure if your pension will be enough?
Informed Decisions are one of Ireland's only remaining independent financial advice firms. Our free retirement calculator models your income, tax, and lifestyle goals — in 10 minutes.
Find out where you stand today...

